


Determining a Budget for a Car
Buying a car is a major financial decision, and figuring out your budget should happen before you start looking at vehicles.
It can be tempting to choose a car based on the monthly payment a dealership gives you, but that doesn't tell you the full cost of ownership. Interest, insurance, fuel, maintenance, repairs, taxes and other expenses can make a significant difference to what you can realistically afford.
Before shopping for a vehicle, take some time to determine how much you can comfortably spend. A realistic car budget can help you avoid taking on a payment that puts unnecessary pressure on your finances.
Key Takeaways
- Your car budget should account for the purchase price, financing, insurance, fuel, maintenance and other ownership costs.
- A lower monthly payment does not necessarily mean you're getting a better deal. A longer loan term can reduce payments while increasing the total interest you pay.
- The 20/4/10 rule can be used as a general guideline, but it shouldn't be treated as a strict rule for every Canadian buyer.
- Your credit score, down payment, interest rate and loan term can all affect how much you pay for a vehicle.
- Use our car loan calculator to estimate your payments before deciding how much you can afford to spend.
Start With Your Overall Monthly Budget
The first step in determining a car budget is looking at your overall finances.
Start with your monthly take-home income and subtract your regular expenses, including:
- Housing
- Utilities
- Groceries
- Insurance
- Phone and internet
- Debt payments
- Savings and investments
- Entertainment and other discretionary spending
The amount left over gives you a better idea of how much room you have for a vehicle.
Don't automatically assume that all of your remaining income should go toward a car. You should still have room for unexpected expenses and other financial goals.
It's also a good idea to look beyond the monthly payment. The Financial Consumer Agency of Canada recommends considering the full cost of a vehicle, including interest, maintenance and insurance, rather than focusing only on the payment.
Before you start shopping, it can also help to understand what determines your monthly car loan payment. This can give you a better idea of how different financing factors will affect your budget.

5 Factors That Affect Your Car Budget
Once you understand your overall finances, several factors will help determine what type of vehicle and financing you can comfortably afford.
1. Your Credit Score
Your credit history can affect the financing options available to you, including the interest rate you may qualify for.
A stronger credit profile can make it easier to qualify for competitive financing, while borrowers with lower credit scores may have fewer options or higher borrowing costs.
Before deciding on a vehicle, it's worth understanding where your credit currently stands. If you have less-than-perfect credit, don't automatically assume that you can't get approved for a car loan. Your income, existing debts, employment and other factors can also be considered by lenders.
If you're wondering what the minimum credit score is to get a car loan, understanding your credit profile is a good place to start.
If your credit needs some work, you may also want to learn how to rebuild your credit with a car loan.
2. Your Down Payment
A down payment reduces the amount you need to borrow.
For example, putting $5,000 down on a $30,000 vehicle means you're financing less than you would if you made no down payment.
A larger down payment can also reduce your monthly payment and the amount of interest you pay over the life of the loan.
That doesn't mean you need to drain your savings to reach a specific down payment percentage. Your emergency fund and other financial priorities should also be considered.
There is no universal down payment amount that works for every buyer. If you're trying to determine how much of a down payment you should make on a car, consider what you can comfortably afford without putting your other finances at risk.
You can also learn more about the relationship between down payments and interest rates when financing a car.
3. Your Loan Term
Your loan term is the amount of time you have to repay the car loan.
A longer term generally means lower monthly payments, but it can also mean paying more interest over the life of the loan.
Canada.ca specifically recommends comparing the total cost of different loan terms rather than simply choosing the payment that fits your monthly budget.
For example, a $25,000 loan at 5% interest costs more overall when financed for 84 months than when financed for 36 months, even though the longer-term payment is lower.
Choose a term based on what you can comfortably afford, not just on how low you can get the monthly payment.
If you're comparing different options, read our guide on how long your car loan term should be.
4. Taxes and Fees
The advertised vehicle price isn't necessarily the final amount you'll pay.
Depending on where you live and the vehicle you're purchasing, you may have to account for sales tax, registration, licensing and other fees.
Make sure your budget is based on the total amount you're actually financing or paying, rather than just the vehicle's advertised price.
This is particularly important when comparing vehicles at different price points. A car that appears affordable based on the sticker price can become significantly more expensive once taxes and financing costs are included.
5. Your Interest Rate
Your interest rate can have a significant impact on both your monthly payment and the total cost of the vehicle.
Two buyers purchasing the same vehicle could end up paying very different amounts depending on their financing terms.
This is why it's useful to compare the total cost of financing instead of looking only at the monthly payment.
Your credit score, loan amount, term and other factors can all play a role in the financing you qualify for.
What About the 20/4/10 Rule?
You may have heard of the 20/4/10 rule for buying a car.
Traditionally, the guideline suggests:
- Putting 20% down
- Financing the vehicle for four years or less
- Keeping vehicle expenses to around 10% of your income
It's a useful starting point, but it shouldn't be treated as a universal rule.
Vehicle prices and ownership costs vary significantly, and not every buyer will be in a position to follow the guideline exactly.
Your actual budget should be based on your income, expenses, savings, transportation needs and other financial goals.
For one person, a $30,000 vehicle may be perfectly manageable. For someone with a different income or significantly higher expenses, the same vehicle could put too much pressure on their budget.
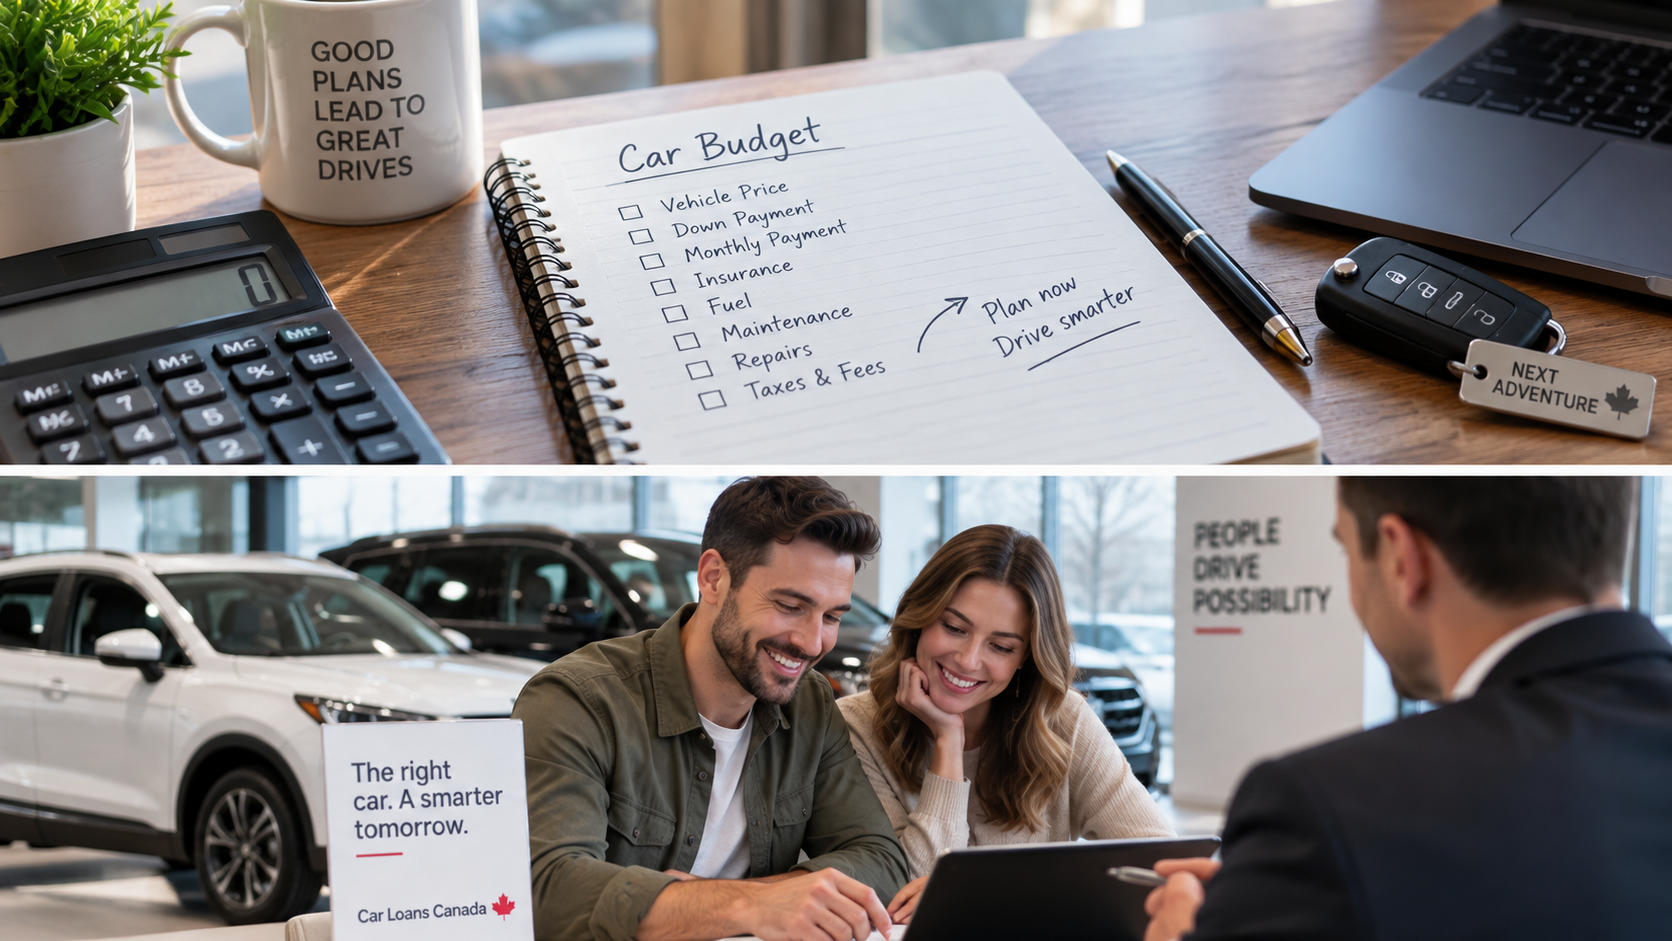
Don't Forget the Cost of Owning the Car
Your car payment is only one part of your transportation budget.
Before buying, consider the ongoing costs of owning the vehicle.
Insurance
Insurance premiums can vary significantly based on your location, driving history, vehicle and coverage.
Get an insurance quote before buying a vehicle so you know what you're actually going to pay.
A vehicle with a lower purchase price isn't necessarily cheaper to own if it comes with significantly higher insurance costs.
Fuel or Charging
Think about how many kilometres you drive each month and how fuel-efficient the vehicle is.
Someone with a long daily commute may spend considerably more on fuel than someone who only drives occasionally.
If you're considering an electric or hybrid vehicle, factor charging or electricity costs into your budget as well.
Maintenance
Regular maintenance can include oil changes, tire changes, brakes, filters and other scheduled services.
The cost varies depending on the vehicle, how much you drive and where you have the work performed.
Maintenance is one reason it's important to consider more than just the purchase price when comparing vehicles.
Repairs
Even a reliable vehicle can eventually require unexpected repairs.
It's a good idea to keep some money available for expenses such as tires, brakes, batteries or other repairs rather than assuming your only vehicle expense will be the monthly payment.
You may also want to consider whether an extended warranty makes sense for your situation. Before purchasing one, understand exactly what is covered and what isn't.
Depreciation
Depreciation is another cost that is easy to overlook.
Your vehicle generally loses value as it gets older and accumulates kilometres. This is particularly important if you expect to sell or trade in the vehicle in the future.
The amount of depreciation can also vary significantly depending on the type, age and condition of the vehicle.
If you're still deciding between a new and used vehicle, our guide on buying a new or used car can help you compare the financing considerations involved with each option.
Use a Car Loan Calculator Before Shopping
Once you've established a general budget, use our car loan calculator to see what different vehicles and financing scenarios could look like.
You can adjust factors such as:
- Vehicle price
- Down payment
- Interest rate
- Loan term
- Trade-in value
- Province
- Payment frequency
The calculator can show your estimated monthly, bi-weekly and weekly payments, along with the estimated total interest paid.
Try running a few different scenarios. For example, compare what happens if you spend $25,000 instead of $35,000, increase your down payment or choose a shorter loan term.
If the numbers don't comfortably fit your budget, that's a sign that you should consider a less expensive vehicle rather than relying on a longer loan term to make the payment work.
Our guide on how a car loan calculator can make car buying easier also explains how to use this type of tool when you're comparing vehicles.
Don't Build Your Budget Around the Lowest Possible Payment
One of the biggest mistakes you can make when buying a car is choosing your vehicle based entirely on the monthly payment.
A dealership may be able to lower your payment by extending the loan term. However, you'll generally pay more interest over a longer term.
Instead of asking, "How low can I get my monthly payment?", ask:
"How much can I comfortably afford to spend on this vehicle without putting my other financial goals at risk?"
That's a much better starting point.
It's also worth comparing financing options before you visit a dealership. Getting your financing arranged ahead of time can give you a better understanding of what you can afford and what financing terms may be available to you.
Read more about why you should arrange car financing before visiting a dealership.
What Car Can You Afford?
There isn't one specific income level that determines what car you can afford.
Your ideal budget depends on your complete financial situation.
If you have low monthly expenses, significant savings and minimal debt, you may be able to comfortably afford a more expensive vehicle. If you have high housing costs, student loans, credit card debt or other financial obligations, a lower vehicle budget may make more sense.
The goal isn't to buy the most expensive car you can qualify for. It's to find a vehicle that meets your needs while leaving enough room in your budget for everything else.
Should You Finance Through a Bank or Dealership?
Once you've established your budget, you'll also need to decide where to arrange your financing.
You can potentially arrange financing through a bank, credit union, dealership or an auto financing company.
Each option can have different requirements and financing terms. If you're comparing your options, take a look at car financing from a bank versus a dealership.
The most important thing is to compare the overall cost of borrowing and make sure the financing fits within the budget you've already established.
Ready to Find a Car Loan?
Once you've determined what you can comfortably afford, the next step is finding financing that fits your budget.
If you're looking for a car loan in Canada, you can apply with Car Loans Canada and explore your financing options.
You can also learn more about how to get a car loan in Canada before starting the application process.
Before applying, use our car loan calculator to estimate different vehicle prices, down payments and loan terms.
Having a realistic budget in place can make the entire car-buying process easier and help you make a more informed decision.
Frequently Asked Questions
How much should I budget for a car?
There is no universal dollar amount that works for everyone. Your car budget should account for your income, existing expenses, debts, savings goals and the ongoing costs of owning the vehicle.
Is the 20/4/10 rule still relevant?
The 20/4/10 rule can be used as a general guideline, but it shouldn't be treated as a strict requirement. Vehicle prices and ownership costs vary, and your budget should reflect your individual financial situation.
Should I focus on the monthly car payment?
No. Your monthly payment is only one part of the total cost. Consider the interest paid over the loan, insurance, fuel, maintenance, repairs, taxes and depreciation when determining what you can afford.
How can I calculate my potential car payment?
You can use our car loan calculator to estimate payments based on the vehicle price, down payment, interest rate, loan term, trade-in and other factors.
Is it better to make a larger down payment?
A larger down payment can reduce the amount you need to finance and may lower your monthly payments and total interest costs. However, you shouldn't put so much money down that you leave yourself without enough savings for emergencies and other expenses.
Should I get financing before going to a dealership?
Getting financing arranged before visiting a dealership can help you establish a realistic budget and understand your financing options. You can still compare the dealership's financing offer against the financing you already have available.
