


If your credit score isn't where you want it to be, you may be wondering how long it will take to improve. The answer depends on what is affecting your credit and what steps you take to address it.
Some people may see changes within a few months, while rebuilding credit after serious issues such as collections, bankruptcy, or multiple missed payments can take considerably longer.
The good news is that you don't have to wait years before you start seeing progress. Credit information is updated regularly, and making consistent, responsible financial decisions can begin improving your credit profile over time.
If you're working toward getting approved for a car loan, improving your credit can also help you qualify for better financing options. You can use our car loan calculator to estimate what your payments could look like, then apply for a car loan with Car Loans Canada when you're ready.
How long does it take to improve your credit score?
There is no exact timeline for improving your credit score in Canada.
If you've recently started making payments on time, paying down credit card balances, or correcting errors on your credit report, you may see changes within a few months. However, the amount your score improves and how quickly it happens depends on your individual credit history.
For someone with a few recent missed payments, improvement may happen relatively quickly once their accounts are brought up to date. Someone with collections, a consumer proposal, or bankruptcy may need several years of consistent financial activity to fully rebuild their credit profile.
The important thing is to focus on building a positive history rather than looking for an overnight increase.
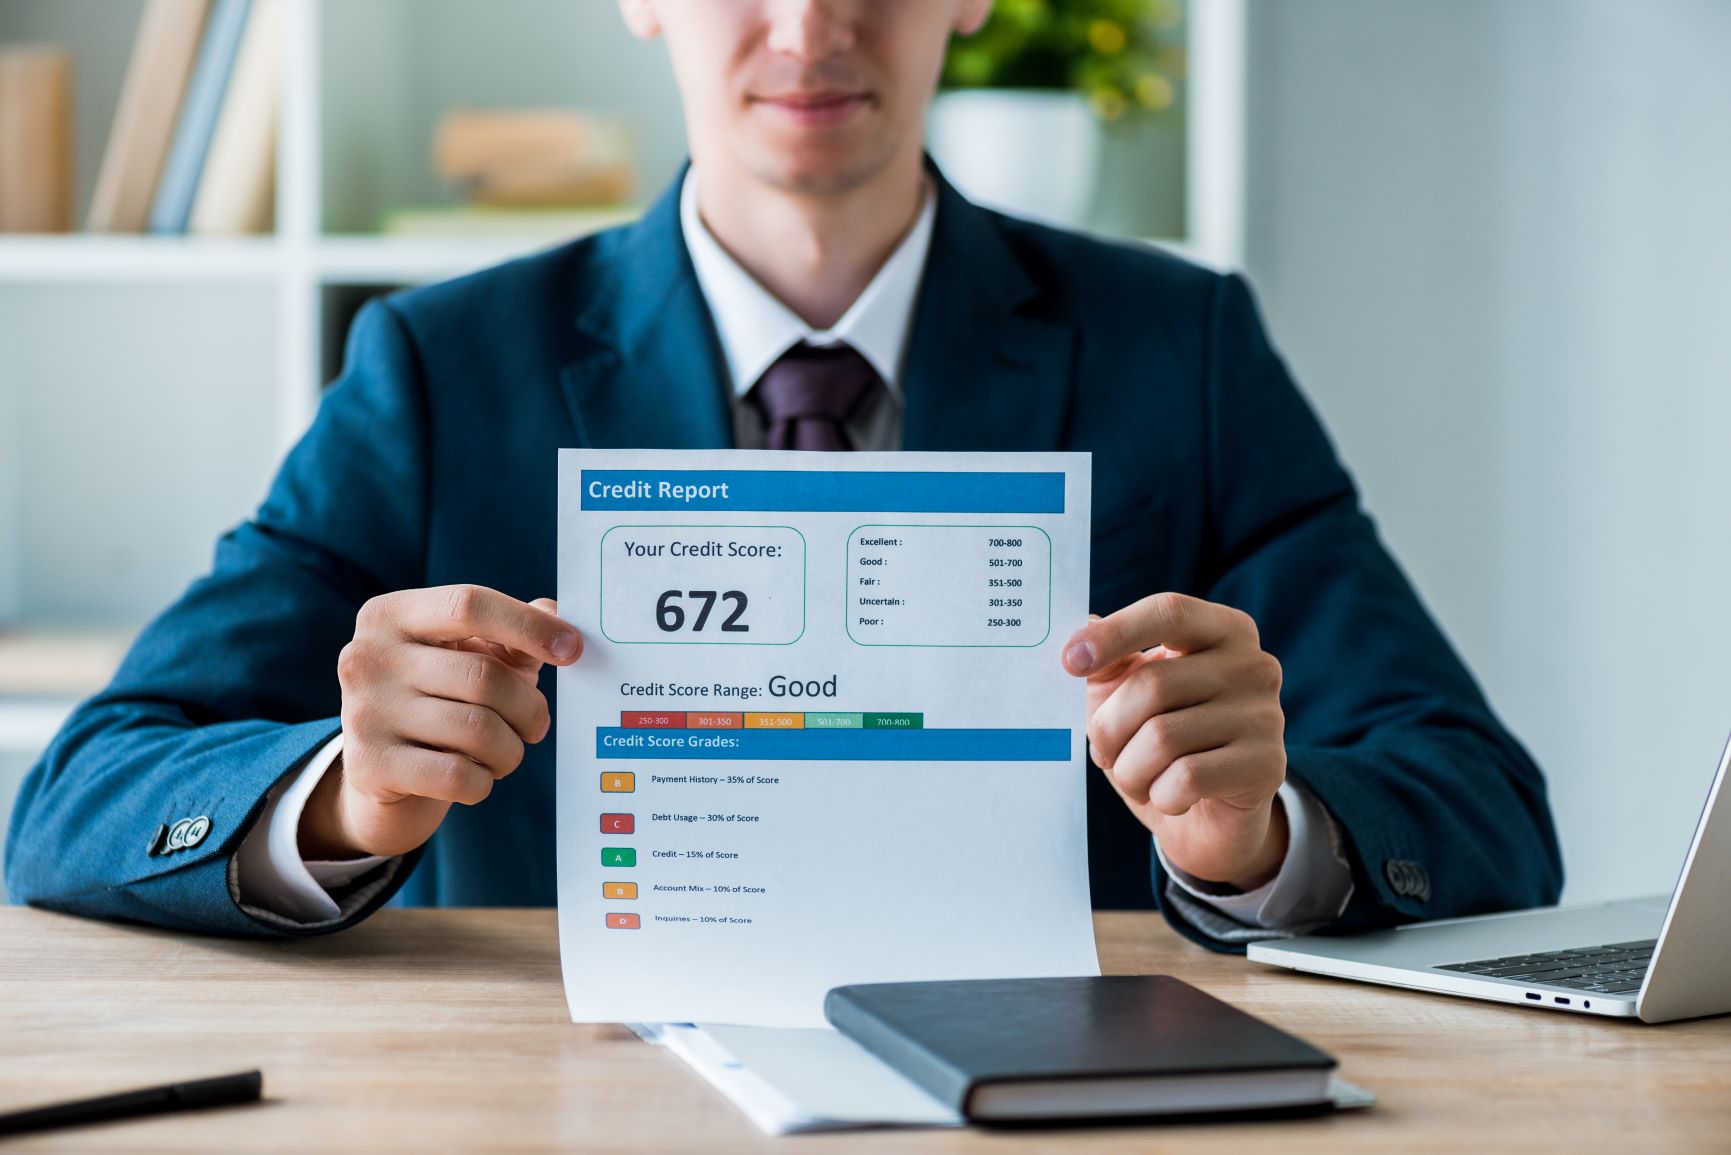
What affects your credit score?
Several factors influence your credit score in Canada. While the exact scoring formulas used by Equifax and TransUnion are not publicly identical, the major factors include:
- Payment history
- Credit utilization
- Length of credit history
- Types of credit
- Recent credit applications
Payment history is particularly important. The Financial Consumer Agency of Canada recommends making payments on time and at least making the minimum payment if you can't pay the full balance.
Your credit utilization also matters. This refers to how much of your available revolving credit you're using. Keeping your credit card balances relatively low compared with your limits can help your credit profile. The Financial Consumer Agency of Canada recommends aiming to use less than 30% of your available credit.
How quickly can paying down debt improve your credit?
Paying down high credit card balances can help your credit profile, particularly if you're using a large percentage of your available credit.
For example, if you have a $5,000 credit limit and owe $4,000, your utilization is 80%. Paying that balance down to $1,500 would reduce your utilization to 30%.
Once your lender reports the updated balance to the credit bureau, your credit score may change. The timing varies because lenders don't all report account activity on the same schedule.
Paying off debt can help, but don't assume every negative item disappears immediately after you pay it. Accurate negative information can remain on your credit report for years.
How long do missed payments stay on your credit report?
A missed payment can continue to affect your credit long after you've caught up on the account.
The exact reporting period depends on the type of information and the credit bureau. TransUnion, for example, says adverse credit information is generally removed six years after the date of first delinquency.
That doesn't mean your credit score will stay low for six years.
The impact of a missed payment can decrease as it becomes older and you establish a stronger history of on-time payments. New positive information can help demonstrate that your financial habits have changed.
How long do collections stay on your credit report?
Collections are more serious than an occasional late payment and can make it harder to qualify for credit.
TransUnion says collection accounts are generally removed six years after the date you defaulted with the original creditor.
Paying a collection is still important, but paying it doesn't necessarily mean the record immediately disappears.
If you have accounts in collections, focus on getting your overall finances back under control and establishing positive payment history going forward.
How does bankruptcy affect your credit?
Bankruptcy can have a significant effect on your credit profile, but it doesn't mean you'll never be able to borrow again.
The length of time a bankruptcy remains on your credit report depends on where you live and whether you've filed bankruptcy before.
For example, TransUnion reports that a first bankruptcy generally remains on file for six years after discharge in several provinces, while in Ontario and Quebec it can remain for seven years after discharge. A second bankruptcy can remain for 14 years.
If you've gone through bankruptcy, rebuilding your credit starts with establishing new positive payment history and keeping your debt manageable.
That can eventually include responsibly managing a car loan, credit card, or other form of credit.
Do credit checks lower your credit score?
It depends on the type of credit check.
A hard inquiry happens when you apply for credit and a lender checks your credit report as part of the application. Hard inquiries can affect your credit score.
A soft inquiry, such as checking your own credit report, does not affect your score.
If you're shopping for a car loan, you don't necessarily need to avoid comparing financing options altogether. The Financial Consumer Agency of Canada notes that credit bureaus may treat multiple car loan inquiries made within a two-week period as a single inquiry for scoring purposes.
How to improve your credit faster
There isn't a legitimate shortcut that can instantly fix your credit. The most effective approach is to consistently make responsible financial decisions.
Start with these steps:
Pay every bill on time
Payment history is one of the most important parts of your credit profile. Set up automatic payments or reminders so you don't accidentally miss a due date.
Pay down credit card balances
Reducing your credit utilization can help strengthen your credit profile.
Avoid unnecessary credit applications
Only apply for credit when you actually need it. Too many applications in a short period can make you appear to be seeking credit urgently.
Keep older accounts open when appropriate
A longer credit history can help your score. If an older account has no annual fee and you can manage it responsibly, keeping it open may help preserve your credit history.
Check your credit reports for errors
Errors on your credit report can negatively affect your ability to get approved for financing. Review your reports and dispute any information that is inaccurate or doesn't belong to you.
TransUnion says disputes are typically investigated within 30 days, although the exact process can vary.
Can a car loan help improve your credit?
Yes, a car loan can help you build positive credit history when you make every payment on time.
A car loan is an installment loan, which can also add another type of credit to your profile. The Financial Consumer Agency of Canada notes that having different types of credit, such as a credit card, car loan, and line of credit, can be beneficial when they are managed responsibly.
If you're considering financing a vehicle while rebuilding your credit, start by figuring out what you can comfortably afford. Use our car loan calculator to compare different vehicle prices, interest rates, down payments, and loan terms.
Once you know what fits your budget, you can apply for a car loan with Car Loans Canada and explore financing options that match your financial situation.
Frequently asked questions
How long does it take to raise your credit score?
There is no fixed timeline. Some borrowers may see changes within a few months, while rebuilding after major negative events can take years. Consistent on-time payments and responsible credit use are the most important factors.
Can I improve my credit score in 30 days?
You may see your credit report and score change within 30 days, particularly if a lender reports a lower credit card balance or an account is brought up to date. However, significant credit improvement usually takes longer.
Does paying off debt improve your credit score?
Paying down debt can help, particularly when it reduces your credit utilization. However, paying an old negative account does not necessarily remove the negative history immediately.
Can I get a car loan while rebuilding my credit?
Yes. There are Canadian lenders that work with borrowers who have less-than-perfect credit. Your interest rate and financing options will depend on factors such as your credit history, income, employment, and overall financial situation.
The Bottom Line
Improving your credit takes time, but you can start making progress today. Pay your bills on time, reduce high credit card balances, limit unnecessary applications, and regularly check your credit reports for errors.
If buying a vehicle is part of your financial plans, don't assume you need perfect credit to get approved. Use our car loan calculator to estimate a payment that fits your budget, then apply for a car loan with Car Loans Canada to explore your financing options.
A stronger credit score doesn't happen overnight, but every responsible payment helps move you in the right direction.
